Risk-to-Reward Ratio in Forex: Why Win Rate Alone Misleads
Published 30 October 2026. All numbers in the examples are hypothetical and are used only to illustrate the maths.
Ask a new trader how they are doing and the answer is usually a win rate: I win seven trades out of ten. It sounds impressive, yet it says nothing about whether the account is growing. A trader who wins 70% of trades can still lose money, and a trader who wins only 40% can be profitable. The missing piece is the risk-to-reward ratio, and how it combines with win rate to produce expectancy. This guide explains all three with simple numbers you can check yourself.
What Is the Risk-to-Reward Ratio?
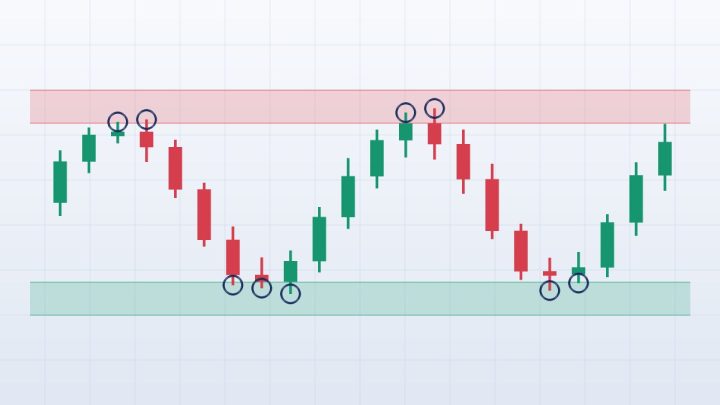
The risk-to-reward ratio compares how much you stand to lose on a trade with how much you aim to gain. Risk is the distance from your entry to your stop loss. Reward is the distance from your entry to your take-profit target.
Suppose you buy EUR/USD with a 20-pip stop and a 40-pip target. You risk 20 pips to make 40, a ratio of 1:2. Many traders call the amount at risk 1R, so this trade risks -1R and targets +2R. Measuring results in R lets you compare trades of different sizes on one scale.
The ratio is only as useful as the levels behind it. A 1:3 target that price rarely reaches is worse than a 1:1.5 target that is hit regularly.
The Break-Even Win Rate
Every ratio has a break-even win rate: the share of trades you must win just to cover your losses, before costs. The formula is simple: break-even win rate = risk ÷ (risk + reward), or 1 ÷ (1 + reward-to-risk).
| Risk-to-reward | Break-even win rate | What it means |
|---|---|---|
| 1:0.5 | 66.7% | You must win two trades in three just to break even |
| 1:1 | 50% | Half of your trades must win |
| 1:1.5 | 40% | Four wins in ten covers the losses |
| 1:2 | 33.3% | One win in three is enough |
| 1:3 | 25% | One win in four is enough |
A higher ratio lowers the win rate you need, but it does not make a strategy profitable. It only sets the bar your strategy has to clear.
Expectancy: Your Average Result per Trade
Expectancy combines win rate with the size of your wins and losses. Measured in R, the formula is: expectancy = (win rate × average win) – (loss rate × average loss). Compare two hypothetical traders:
- Trader A wins 40% of trades, averages +2R on winners and loses 1R on the rest: (0.40 × 2) – (0.60 × 1) = +0.2R per trade. Over 100 trades that is about +20R.
- Trader B wins 70% of trades but averages only +0.3R on winners and loses 1R on the rest: (0.70 × 0.3) – (0.30 × 1) = -0.09R per trade. Over 100 trades that is about -9R.
If both risk 1% of their account on each trade, Trader A gains roughly 20% and Trader B loses roughly 9%, before costs and compounding. Trader B has the more impressive win rate and the worse account.
These figures illustrate the idea; they are not results to expect. Real expectancy comes from your own recorded trades, and a few dozen trades is a weak sample. The more trades you record, the more reliable the number becomes.
How Spreads and Costs Change the Maths
Costs make losing trades slightly bigger and winning trades slightly smaller, so they quietly shift the ratio. Take the EUR/USD example again. Say you measure a 20-pip stop and a 40-pip target from the bid price on the chart, but your buy order fills at the ask, 1.2 pips higher. Your real risk is 21.2 pips and your real reward is 38.8 pips. That is a ratio of about 1:1.83, not 1:2, and the break-even win rate rises from 33.3% to about 35.3%.
Commissions and slippage push the figure further. This is also why very tight stops on small targets are expensive: the same spread is a much larger share of the trade. Read our guide to forex spreads to see how to pay less. Spreads can widen sharply around major releases, such as the Bank of England decision on 5 November, which changes the real ratio of any trade opened at that moment.
How to Use Risk-to-Reward in a Trade Plan
- Place the stop where the idea is wrong. Use market structure or volatility, not a distance chosen to make the ratio look good.
- Pick a realistic target. Use a level where price has reacted before rather than a number you hope for.
- Measure the ratio from your real entry, including the spread.
- Skip trades below your minimum. Many traders set a floor between 1:1.5 and 1:2, but the right figure depends on your win rate and costs.
- Size the position from the stop. Decide the percentage of your account you will risk, then let the stop distance set the lot size. Our lot size guide and risk management calculator do the arithmetic.
- Record every result in R. A trading journal turns your expectancy into data instead of a feeling. Our guide on using the Hamro Trading Journal shows how.
Write these rules into your trading plan so you are not deciding them in the middle of a trade.
Common Mistakes
- Forcing large ratios. Pushing every target out to 1:5 can lower the win rate so much that expectancy falls.
- Moving the stop after entry. Widening a stop changes the ratio you agreed to. If a trade only works with a wider stop, the original plan was flawed.
- Cutting winners early. Taking small profits while letting losses run to the full stop reverses the ratio you planned.
- Ignoring correlation. Long positions in EUR/USD and GBP/USD can behave like one trade with double the risk. The currency correlation tool helps you check.
- Judging a strategy on a handful of trades. Even a profitable system will produce losing streaks.
- Revenge trading. Chasing a quick recovery after a loss usually means breaking the rules that create your ratio. Our trading plan guide is a good place to write down limits for losing days.
A Worked Example Over Ten Trades
Imagine ten trades, each risking 1R with a 1:2 target. Four reach the target (+8R) and six are stopped out (-6R). The net result is +2R, a win rate of 40% and an expectancy of +0.2R per trade. Risking 1% per trade, that is about +2% before costs. If costs averaged 0.1R per trade, the net would fall to roughly +1R.
Now change one habit. Suppose one of the four winners reaches +2R, but the other three are closed early at +1R because the trader got nervous. The wins add up to +5R, the six losses still cost -6R, and the same ten trades finish at -1R. The entries and the stops did not change; only the handling of winners did.
What the Evidence Says About Retail Traders
In 2018 the European Securities and Markets Authority reported that analyses by national regulators found 74% to 89% of retail CFD accounts typically lose money, according to the ESMA announcement. Those figures cover CFDs broadly and are several years old, and they do not prove that any single technique solves the problem. They do show why controlling the risk on every trade matters, particularly when leverage magnifies both gains and losses. Our guide to leverage and margin explains how.
Key Takeaways
- Win rate alone does not show whether a strategy makes money. Pair it with the average win and average loss.
- Break-even win rate = 1 ÷ (1 + reward-to-risk).
- Expectancy measured in R is the number worth tracking over time.
- Measure the ratio from your real entry price, including the spread.
- Set stops by market structure, then decide whether the trade is worth taking.
This article is for education only and is not investment advice. Trading leveraged products carries a high risk of loss, and you can lose more than you expect.
Source
Learn more: who we are · the risk disclaimer · contact us.
Educational content, not financial advice. Leveraged trading can lose more than your deposit.